Market overview of the Insulated Concrete Form Market
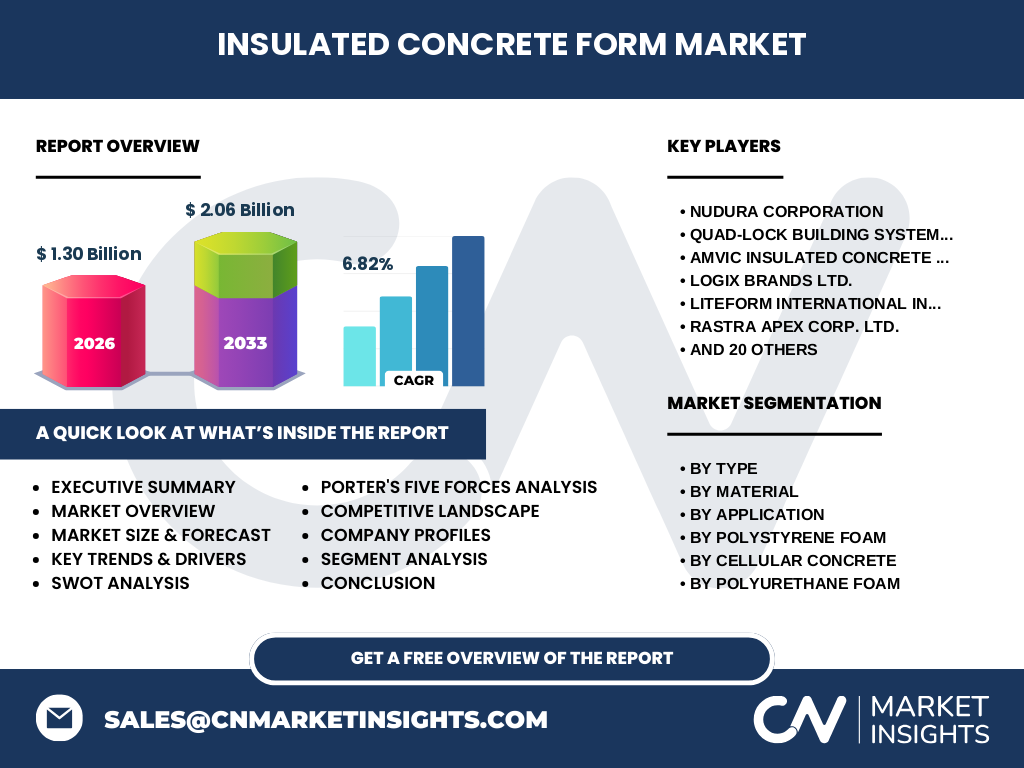
Our analysis indicates that the Insulated Concrete Form Market represents a transformative shift in structural engineering, valued at $1.30 Billion in 2026. This sector encompasses high-performance building systems utilizing expanded or extruded polystyrene foam combined with reinforced concrete. These assemblies deliver superior thermal mass and structural rigidity, fundamentally altering energy efficiency standards across commercial, industrial, and residential developments globally.
What are the key market drivers, restraints, challenges, and opportunities shaping the Insulated Concrete Form Market?
Stringent global energy codes act as primary structural growth drivers, mandating superior building envelope performance. However, high upfront material costs and specialized labor shortages constrain broader adoption. Opportunities lie in integrating advanced polyurethane foam and cellular concrete technologies to meet net-zero carbon mandates, providing developers with enhanced thermal resistance and long-term operational savings.
Emerging trends and growth patterns in the Insulated Concrete Form Market
The shift toward disaster-resilient construction has accelerated demand for robust wall assemblies capable of withstanding extreme weather events. Builders increasingly leverage cement-bonded wood fiber and precast cellular concrete blocks to improve acoustic insulation and fire resistance. Our research highlights that urban developers now prioritize these modular systems to accelerate project timelines while complying with strict environmental regulations.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted global supply chains for petrochemical raw materials like expanded polystyrene, causing severe project delays. However, post-pandemic recovery heavily favored modular, low-labor construction methods. Insulated Concrete Form Market industry trends reflect a permanent pivot toward off-site fabrication and resilient building envelopes, propelling the sector toward a robust valuation of $2.06 Billion by 2033.
Competitive Benchmarking
The competitive landscape features a mix of established innovators and regional specialists. Companies like Nudura Corporation, Quad-Lock Building Systems Ltd., and Amvic Insulated Concrete Forms dominate through proprietary interlocking web designs. Meanwhile, regional players such as Durisol UK Ltd. and KORE Group Holdings Inc. focus on localized cement-bonded wood fiber and expanded polystyrene solutions to reduce freight logistics burdens.
Executive Summary: High-Level Synthesis
The Insulated Concrete Form Market analysis demonstrates an exceptional 6.82% CAGR from 2027 to 2033, scaling from $1.30 Billion to $2.06 Billion. Driven by tightening ASHRAE and European Green Deal energy standards, the sector is transitioning from a niche alternative to mainstream construction. Market participants must invest in automated manufacturing and lightweight material formulations to capture expanding commercial and infrastructural demand.
Market Forecast from 2027 to 2033
Based on our econometric modeling, the Insulated Concrete Form Market size will expand from $1.30 Billion in 2026 to reach $2.06 Billion by the end of 2033, expanding at a steady 6.82% CAGR. This trajectory is underpinned by massive urbanization initiatives, rising commercial retrofitting mandates, and government subsidies incentivizing high-efficiency building envelopes across North America and Europe.
Segmentation Analysis of the Insulated Concrete Form Market
Our research segments the market across types, materials, and applications. Type categories include Waffle Grid System, Flat Wall System, and Post & Beam System. Material segments span Polystyrene Foam (divided into Expanded Polystyrene (EPS) and Extruded Polystyrene (XPS)), Polyurethane Foam, Cement-bonded Wood Fiber, and Cellular Concrete, catering to diverse structural load and thermal insulation requirements.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly due to local building codes and climate exposure. North America leads in adoption, driven by hurricane-prone coastal zones favoring flat wall systems and expanded polystyrene blocks. Europe follows closely, propelled by nearly zero-energy building (nZEB) regulations that heavily reward superior thermal mass and airtight construction methodologies provided by innovators like JACKON Insulation GmbH and ISO SPAN Baustoffwerk GmbH.
In-Depth Regional Review
A detailed examination of regional markets reveals rapid growth in developing economies where rapid urbanization demands disaster-resilient infrastructure. In contrast, mature markets in Western Europe and North America prioritize energy retrofits. Logistical constraints heavily influence regional pricing, favoring localized manufacturing footprints established by firms such as BuildBlock Building Systems LLC and Logix Brands Ltd. near major transportation hubs.
Strategic Company Profiles
Leading industry participants maintain competitive moats through continuous product innovation and patent portfolios. Airlite Plastics Company and Amvic Insulated Concrete Forms leverage advanced molding technologies to enhance R-values. Meanwhile, specialized operators like Sismo Inc. and Rastra Apex Corp. Ltd. focus on customized, project-specific geometric designs, capturing high-end architectural and commercial segments.
Porter's Five Forces Analysis
The threat of new entrants remains moderate due to high capital expenditures required for proprietary molding tooling. Bargaining power of suppliers is high, as petrochemical resin costs dictate margin pressures. Competitive rivalry is intense among established leaders like Nudura Corporation and Quad-Lock Building Systems Ltd., forcing continuous differentiation through installation speed and thermal efficiency certifications.
SWOT Analysis of the Industry
Strengths include unmatched thermal performance and structural resilience. Weaknesses stem from higher initial material outlays compared to traditional wood framing. Opportunities abound in commercial warehousing and infrastructural sound barriers using cellular concrete and rigid polyurethane foam. Threats involve volatile raw material costs and stringent, evolving local fire safety certifications.
Value Chain Analysis
The value chain originates with petrochemical refiners supplying EPS and XPS beads, followed by form molders and proprietary interlocking web manufacturers. Distributors and specialized contractors bridge the gap to end-users in commercial and residential sectors. Margin concentration heavily favors upstream resin suppliers and downstream technical engineering firms offering comprehensive builder training.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in cement-bonded polystyrene beads and precast cellular concrete blocks, as these materials offer superior sustainability profiles. Strategic investments in automated assembly lines and digital BIM (Building Information Modeling) integration plugins will yield the highest returns by reducing on-site installation errors for commercial developers.
Conclusion and Key Takeaways
The Insulated Concrete Form Market industry trends confirm that energy efficiency and structural resilience are non-negotiable in modern real estate. With the market projected to reach $2.06 Billion by 2033 at a 6.82% CAGR, early movers investing in advanced composite materials and installer education networks will secure long-term market dominance.
Research Methodology
Our baseline estimates are triangulated using a rigorous mix of primary stakeholder interviews with c-suite executives from firms like Liteform International Inc. and SuperForm Products Ltd., combined with secondary trade registry data, customs import-export logs for polystyrene resins, and macroeconomic construction spending indices across global markets.
Scope of the Report
This report evaluates the Insulated Concrete Form Market across four core material categories, three system types, and four end-use applications from 2026 to 2033. Geographic scope covers North America, Europe, Asia-Pacific, and Rest of World. Limitations include exclusion of unverified artisan form-work and localized custom pours not utilizing standardized commercial interlocking blocks.
Recent Developments and Strategic Moves
Recent industry momentum is characterized by strategic acquisitions and capacity expansions. Market leaders have invested heavily in eco-friendly blowing agents and recycled polymer content. Partnerships between technology providers like KORE Group Holdings Inc. and regional builders aim to streamline zero-carbon commercial construction, directly influencing Insulated Concrete Form Market growth trajectories.